

Financial Stability
7 ways to make Europe’s banking framework work better for growth
Published on 01 October 2026
Europe needs banks that are resilient, but also able to finance businesses, investment and innovation. So what could make the banking framework work better? In its latest contribution to the European Commission, the ABBL identifies seven areas where a more proportionate, integrated and workable approach could make a real difference.
Summary
On 17 September, the ABBL submitted its contribution on EU Banking Sector Competitiveness and Single Market Integration, turning the debate on competitiveness into concrete proposals for the European banking framework.
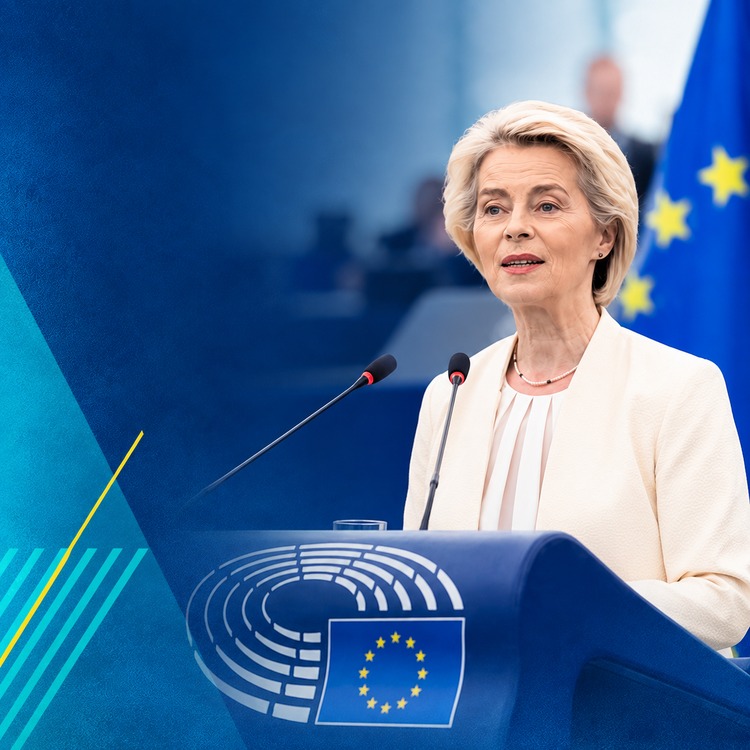
The question has become increasingly urgent. In her 2026 State of the Union address, European Commission President Ursula von der Leyen called for a banking system built for growth as well as stability, alongside simplification and reduced fragmentation.
For the ABBL, strengthening competitiveness does not mean weakening safeguards. It means making regulation more coherent, proportionate and risk-sensitive, so that financial resilience is preserved while banks retain the capacity to support the real economy.
So, where could Europe make a difference?
Related publications
-
-
ABBL position paper on EU banking sector competitiveness and Single Market integration published on 17 September 2026

7 ways to make the framework work better
1. Make capital requirements work together
European banks operate under several layers of prudential requirements, buffers and backstops. Over time, this has created an increasingly complex framework, with unnecessary overlaps in some areas.
The ABBL supports an ambitious review of the overall architecture of capital requirements to remove those overlaps, restore risk sensitivity and ensure capital can be allocated efficiently to financing the European real economy, while preserving financial stability.
The objective is not lower resilience, but a framework in which the different requirements work coherently together.
2. Base proportionality on actual risk
Size alone does not determine how complex or risky a bank is.
Regulatory and supervisory requirements should therefore better reflect an institution’s actual risk profile, complexity, activities and business model, rather than relying predominantly on balance-sheet size.
The ABBL also calls for the Small and Non-Complex Institution framework to be revisited so that it better reflects risk and complexity in practice.
A genuinely risk-based approach allows regulation to remain robust without applying the same treatment to fundamentally different institutions.
3. Make the Single Market work across borders
A Single Market should make it easier to operate and provide services across Europe. In practice, cross-border banks still face national gold-plating, administrative differences, options and discretions, and divergent supervisory expectations.
For Luxembourg, where cross-border banking is structural, these frictions are particularly relevant.
The ABBL calls for greater use of common standards, notably for digital onboarding, KYC, client protection and cross-border services, as well as greater supervisory convergence.
But convergence should not automatically mean further centralisation. National supervisory expertise and proximity remain valuable, which is why the ABBL favours a convergence-first approach.
4. Report once, not several times
Simplification becomes very concrete when the same or similar information has to be reported under overlapping European and national requirements.
The ABBL supports a genuine “report once” principle: eliminate unnecessary duplication, harmonise definitions and data standards, and improve information-sharing between authorities.
New requirements should also be systematically checked against obligations that already exist. Importantly, simplification should tackle the underlying regulatory overlaps, not merely make the reporting interfaces easier to use.
5. Preserve different banking models
Europe’s banking ecosystem is diverse, and this diversity is an asset.
Private banks, wealth managers, depositary and custodian banks, specialised institutions and medium-sized banks perform different functions and face different risks. Competitiveness reforms should work for this whole ecosystem.
The EU should also remain attractive to international banking groups through requirements that are proportionate, predictable and operationally workable.
The same applies to talent. An attractive and competitive remuneration framework remains important if Europe wants to attract and retain the expertise its financial sector needs.
6. Make it easier to innovate safely
Innovation is not separate from competitiveness. It is one of its drivers.
The ABBL calls for digital legislation to be better aligned and simplified, with technology-neutral, risk-based rules, greater use of regulatory sandboxes and more public-private experimentation.
The goal is straightforward: enable digital services to be developed and scaled across Europe faster and safely, while maintaining appropriate safeguards.
7. Design rules that can work in practice
A regulation can pursue the right objective and still create unnecessary complexity if its interaction with other requirements or its implementation timeline is not considered early enough.
The ABBL therefore calls for the cumulative impact of requirements, their interaction with existing frameworks and their implementation in peer jurisdictions to be assessed systematically.
Greater regulatory stability, legal certainty and realistic implementation timelines are also needed.
Competitiveness and operational feasibility should be built into regulatory design from the start, rather than addressed only once implementation difficulties emerge.

Reducing unnecessary complexity and fragmentation is key to building a banking framework that preserves resilience while supporting investment, innovation and growth.
Alexandre Dias
Adviser – Financial Markets & ESG
Read the ABBL’s full response
These seven priorities are drawn from the ABBL’s detailed response to the European Commission’s consultation on the competitiveness of the EU banking sector.
 Why this matters beyond banking
These priorities are not about reducing safeguards. They are about making the framework more coherent, proportionate and workable.
For businesses, the benefits are practical: a more integrated Single Market can reduce frictions in cross-border services, a more efficient regulatory framework can free resources for lending and investment, and clearer digital rules can help innovative services scale more effectively across Europe.
As the ABBL has already highlighted in its Hot Topic, Reinforcing the EU banking sector: a catalyst for the growth of Europe, Europe’s growth, digital transition, security and investment ambitions all depend on a financial system capable of mobilising financing at scale.
From identifying barriers to building solutions
The ABBL’s role is not simply to identify complexity. It is to turn the practical experience of Luxembourg’s banking sector into concrete proposals that can make the framework work better.
This means identifying where rules overlap, where national differences create unnecessary obstacles, and where greater proportionality, legal certainty or operational feasibility can support both resilience and growth.
The ABBL will continue to work with the European Commission and EU and national stakeholders to help translate the competitiveness agenda into practical, proportionate and workable solutions.
Related news
-
 Financial Stability
17 September 2026
From political momentum to action: building a more competitive European banking system
> See all news
Alexandre Dias
Adviser – Financial Markets & ESG
Published on 01 October 2026