

Digital, Innovation, Payments
When AI agents pay: banks face a new trust challenge
Published on 21 October 2026
AI agents may soon search, compare, choose, buy and pay on behalf of customers. At Paperjam’s 10×6 Finance Forward, Arnaud Clément from the ABBL explored what this shift could mean for payments, from authentication and liability to European sovereignty, and why banks could become the trusted layer of the emerging agentic economy.
Summary
What happens when the person making a payment is no longer the person behind the account?
That was the question at the heart of Arnaud Clément’s presentation at Paperjam Club’s 10×6 Finance Forward, held on 13 October at Kinepolis Kirchberg.
The event brought together ten speakers from across Luxembourg’s financial centre to share their perspectives on the transformations shaping the future of finance. Artificial intelligence, tokenisation, savings mobilisation and interconnected risks featured prominently, with trust and responsibility emerging as a common thread.
For Arnaud Clément, Head of Payments & Innovation at the ABBL, one of the most important changes could happen almost invisibly: AI agents beginning to make payments on behalf of customers.
 From “you pay” to “it pays”
Today, the payment journey is still centred on the individual.
A customer searches for a product, compares the options, chooses one, proves their identity and authorises the payment.
But in an increasingly agentic economy, that sequence could change significantly.
An AI agent could search, compare, choose, buy and ultimately initiate the payment itself. As Arnaud framed it during his presentation:
The most important payment innovation of the next decade may be the payment you never see.
Arnaud Clément
Head of Payments and Innovation, ABBL
The shift matters because payment systems have traditionally been built around one fundamental question: is this really the customer, and did they approve the transaction?
When an AI agent acts on the customer’s behalf, that question becomes more complex.
 From KYC to KYA
For two decades, financial institutions have become accustomed to Know Your Customer — KYC.
Arnaud argued that autonomous agents could add another layer: Know Your Agent — KYA.
The bank may increasingly need to understand not only who the customer is, but also:
- which agent is acting;
- who operates or provides it;
- which customer it represents;
- what mandate the customer has given it;
- and the precise limits of that mandate.
Once software begins making decisions and taking action, the question becomes who authorised it and within what limits.
The underlying challenge is one of visibility. Once a customer delegates an action to an agent, identity, mandate and consent need to remain verifiable even if the customer is no longer present at the moment of payment.
 When automation meets instant payments
The challenge becomes even more acute when autonomous decision-making meets instant payments.
An agent could make a decision independently and the payment could leave the account immediately. If something is wrong — the product, the amount, the merchant or even the original instruction — there may be very little time to intervene.
As Arnaud put it:
AI removes the human from the decision. Instant payments remove time from the equation.
Arnaud Clément
Head of Payments and Innovation, ABBL
This raises a question that goes far beyond technology:
who is responsible when an AI-enabled payment goes wrong?
The customer? The bank? The merchant? The AI provider? The payment scheme?
Arnaud’s answer was deliberately simple: “That is not a technology question. It is a trust question.”
 The layer above the payment rails
The debate also has a European dimension.
Europe is investing heavily in its payment infrastructure, including instant payments and the digital euro. But AI agents do not necessarily operate within those payment rails themselves. They sit one layer above them, making decisions about when and how those rails are used.
Arnaud distinguished between:
The rails
Instant payments, the digital euro and the infrastructure that moves money.
The layer above
Agents, mandates, identity and consent — the elements that determine whether a transaction was actually authorised.
His warning was that Europe could secure sovereignty over the rails while remaining dependent on non-European technology at the layer where the decisions are actually made.
A role for banks – and for the ABBL
This does not necessarily make banks less relevant. It could make their role in establishing trust even more important.
Someone will still need to verify the identity of the agent, hold and interpret its mandate, record consent and determine whether a particular action was within the permissions granted by the customer.
But these questions cannot be solved by one institution alone.
Identity, mandates, liability, fraud, technology and regulation all cross institutional boundaries.
This is where Arnaud sees a specific role for the ABBL.
For decades, the Association has provided a neutral forum where Luxembourg’s banking community can work collectively and engage with regulators, policymakers and the wider market.
In an agentic economy, that convening role could become particularly important. Banks, fintechs, technology providers and supervisors will need shared rules of trust — and those rules will need to be developed across the ecosystem, rather than within individual institutions.
The objective is therefore not to wait for the architecture of agentic payments to emerge, but to help shape it while the technology is still developing.
Making trust visible
Arnaud concluded with a choice for banks.
They can remain the invisible infrastructure beneath transactions increasingly controlled by someone else’s intelligence.
Or they can become the trusted layer that makes identity, consent and authorisation visible in an otherwise increasingly invisible payment journey.
His closing message captured the argument in one sentence: “When payments become invisible, trust must become visible.”
That idea also reflected the wider discussion at Finance Forward, where speakers repeatedly returned to trust as a defining requirement for an increasingly automated and interconnected financial system.
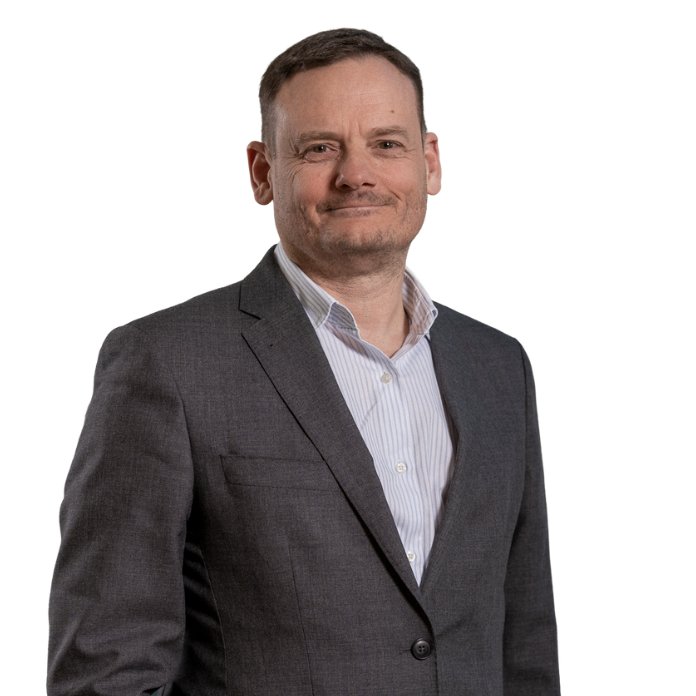
Arnaud Clément
Head of Payments and Innovation, ABBL
Published on 21 October 2026