

Retail Banking
Retail banking: three everyday challenges that require collective solutions
Published on 23 October 2026
Access to banking services, housing finance and fraud prevention affect people and businesses every day. At its annual press conference, the ABBL Retail Banking Cluster set out how banks are responding to these challenges, and why lasting solutions require action beyond the banking sector alone.
Summary
Retail banking is changing rapidly. Customers increasingly expect digital, accessible and secure services, while banks operate in an environment shaped by economic uncertainty, regulatory requirements and increasingly sophisticated fraud.
Against this backdrop, the ABBL Retail Banking Cluster brought together the sector’s latest figures, initiatives and proposals around three concrete issues: preserving access to banking services, supporting a sustainable recovery of Luxembourg’s housing market and strengthening the fight against fraud.
Retail banks play an essential role in the everyday lives of citizens and businesses. Our responsibility is to give them access to the services they need, finance their projects on sustainable terms and protect their transactions. This requires us to continuously adapt our practices, but also to work with all relevant stakeholders.
Laurent Zahles
Chairman of the ABBL Retail Banking Cluster and CEO, Banque Raiffeisen
 Banking is becoming more digital, but access must remain universal
The way customers use banking services continues to evolve.
In 2025, 97% of wire transfers were initiated electronically, compared with 86% in 2019. At the same time, physical banking networks are changing, with some branches increasingly focused on higher-value advisory services and the shared Bancomat ATM network helping to maintain nationwide access to cash.
Digitalisation, however, does not remove the need to ensure that services remain accessible to everyone. Banks are continuing their work to implement European accessibility requirements and adapt their customer journeys accordingly.
97%
of wire transfers were initiated electronically in 2025
up from 86% in 2019
Access to bank accounts is another important part of the equation.
The ABBL’s annual survey recorded more than 51,000 personal account openings in 2025. Participating institutions also opened 7,633 business accounts, an increase of 6.6%.
Yet some companies and project promoters continue to encounter difficulties when establishing a banking relationship. Complex ownership structures, incomplete documentation, geographical or sanctions-related risks, specialist business models or simply a mismatch with a bank’s commercial model can all make the process longer or more complex.
To help address these situations, the ABBL has established its Business Support Desk, a free and confidential service for legal entities experiencing difficulties in establishing a banking relationship.
The ABBL acts as a facilitator, helping applicants understand possible obstacles, the information generally required and, where appropriate, facilitating dialogue with the institution concerned. It does not replace banks in their individual decision-making.
+6.6%
increase in business account openings in 2025
7,633 business accounts opened
Source: ABBL annual survey
 Housing: credit is available, but confidence remains a key obstacle
Luxembourg’s housing market is showing signs of stabilisation after the sharp increase in interest rates, but the recovery remains uneven.
Variable rates on new mortgage loans, which reached 5.02% in December 2023, stood at 3.19% in August 2026.
New mortgage contracts amounted to €6.70 billion in 2025, up 11.9% from 2024. Over the first eight months of 2026, however, volumes remained 8.3% below the same period of the previous year.
The most striking difference is between existing housing and new construction.
Transactions involving existing apartments have returned close to their pre-crisis average. By contrast, only 225 off-plan, or VEFA, transactions were recorded in the second quarter of 2026, around 68% below the average for the same quarter between 2017 and 2021.
This distinction matters.
Existing homes and VEFA properties are financed in the same banking environment and under the same general interest-rate and lending conditions. Buyers are nevertheless returning to the existing-property market while remaining much more reluctant to commit to new construction.
Credit availability alone therefore does not explain the weakness of the new-build market.
Concerns around construction delays, developer failure and completion guarantees have become an important factor in buyers’ decisions.
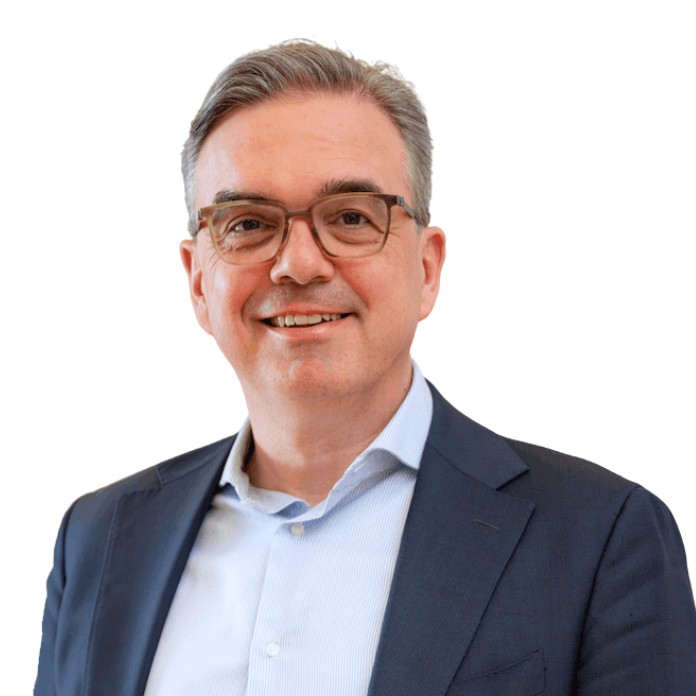
The message is very clear: we want to finance projects and we are doing everything we can to do so. But financing is only one part of the equation. We need to act simultaneously on financing, the economic viability of projects and buyer confidence.
Claude Hirtzig
Chair of the ABBL Retail Banking Cluster and Senior Vice President, Head of Department, Retail & Professional Banking, Spuerkeess.
 Three areas for action
The ABBL is proposing action on three complementary fronts.
First, financing conditions could be made more flexible for viable projects without weakening prudential safeguards. This includes greater recognition of alternative collateral for buy-to-let investments and targeted adjustments to loan-to-value limits.
Second, confidence in VEFA needs to be restored. The ABBL is calling for clearer responsibilities and information requirements across the different parties involved in a project, as well as a level playing field between providers of completion guarantees.
Where a project encounters difficulties, the priority should be to complete the property whenever this remains materially and legally possible, rather than immediately resorting to reimbursement.
Third, the overall viability of property investment needs attention, including the treatment of energy-renovation investments and the attractiveness of the rental market.
The objective is not to loosen lending standards indiscriminately. It is to create the conditions in which economically viable, legally secure projects can genuinely be financed.
 Fraud increasingly starts before the payment
The third challenge discussed by the Retail Banking Cluster concerns fraud.
As financial services become more digital, fraudsters are also becoming more sophisticated. Artificial intelligence can make fake messages, impersonation attempts and fraudulent calls increasingly convincing.
And importantly, many scams begin well before a payment reaches the banking system.
A victim may first encounter a fraudulent advertisement, online platform, text message or telephone call and only later be manipulated into authorising a transaction.
Banks are strengthening prevention and detection measures, including through the introduction of verification of the payee for credit transfers.
But protecting the payment itself is no longer enough.
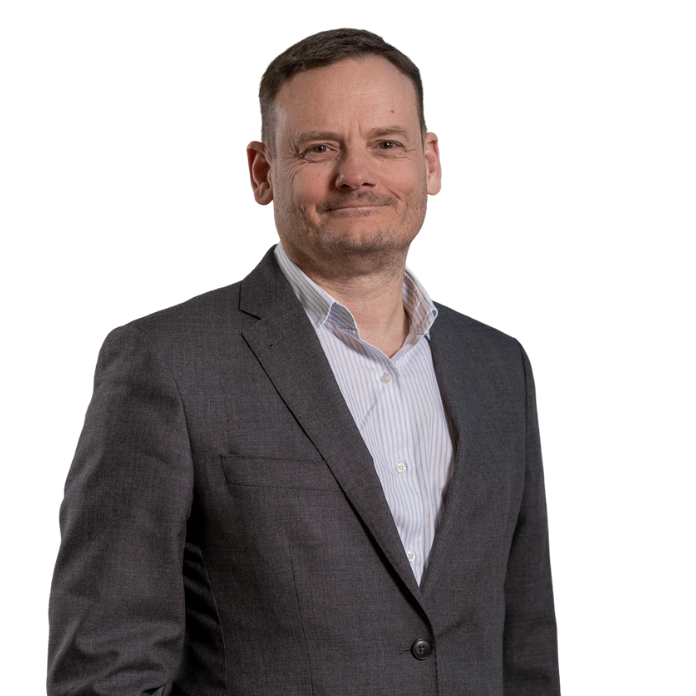
Fraudsters now exploit an entire chain of services and communication channels to reach their victims. Banks must of course strengthen their protective measures, but they cannot act alone. By also mobilising telecom operators, digital platforms and public authorities, we can intervene earlier, prevent fraud more effectively and support victims.
Arnaud Clément
Head of Payments and Innovation, ABBL
The ABBL and the Fondation ABBL pour l’Éducation Financière are also working with the Luxembourg House of Cybersecurity and other partners through the national cyberfraud.lu campaign, helping people recognise common fraud scenarios and understand what to do if they have been targeted.
From banking challenges to shared challenges
Access to accounts, housing finance and fraud prevention may appear very different, but they share the same underlying reality.
Banks have important tools at their disposal, but they do not control every factor that determines the outcome.
Making account opening easier requires a balance between simpler procedures and regulatory obligations. Reviving housing construction requires viable projects, clear legal frameworks and buyer confidence as well as financing. Preventing fraud requires action at the point where scams begin, often outside banking channels altogether.
Through its Retail Banking Cluster, the ABBL will continue working with its members, public authorities and other stakeholders to turn the sector’s proposals into concrete improvements for households and businesses.
Read the press release
Simone Kayser
Senior Adviser - Retail Banking
Published on 23 October 2026